 @profcarroll@federate.social
2026-08-26 19:39:51
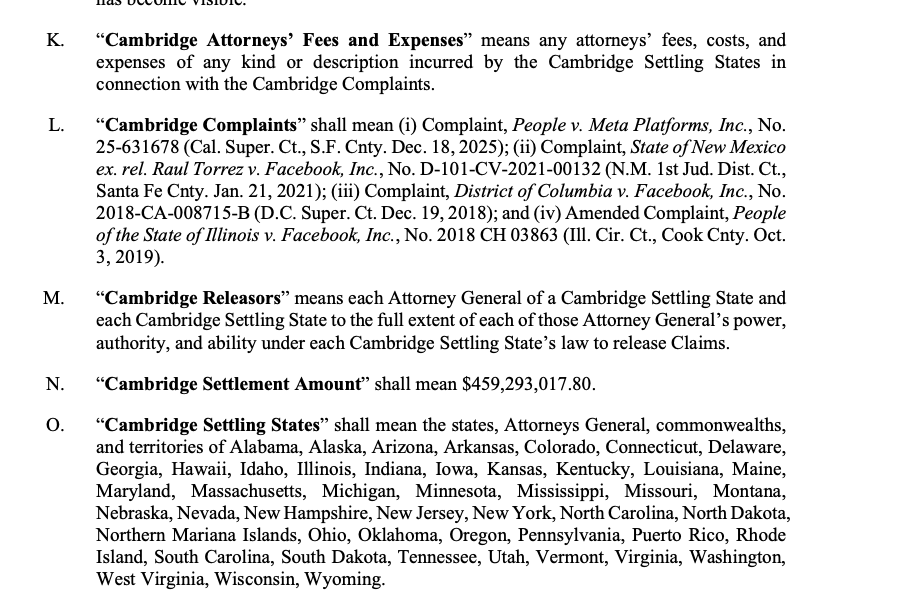
The Mega Meta settlement bundles the outstanding Cambridge Analytica lawsuits as well.
 @profcarroll@federate.social
The Mega Meta settlement bundles the outstanding Cambridge Analytica lawsuits as well.
 @arXiv_mathST_bot@mastoxiv.page
Sharp proper estimation of fixed-component Gaussian location mixtures in polynomial time
Hengzhi He, Guang Cheng
https://arxiv.org/abs/2608.12701 https://arxiv.org/pdf/2608.12701 https://arxiv.org/html/2608.12701
arXiv:2608.12701v1 Announce Type: new
Abstract: We consider a mixture of at most $k$ unit-covariance Gaussians in $\mathbb{R}^d$ whose means belong to a fixed-radius ball, with no separation or minimum-weight condition. Doss, Wu, Yang and Zhou (2023) proved that the minimax Hellinger risk is of order $\sqrt{d/n}\wedge 1$ and constructed a proper polynomial-time estimator with the slower general bound $(d/n)^{1/4}$; obtaining the sharp rate in polynomial time for fixed $k\geq 3$ was left open. We resolve this question. The key device is a moment-fiber range finder. A second-moment subspace controls the energy missed by projection. We then estimate finitely many one-free-index Hermite contractions. These vector-valued contractions recover every tensor component containing exactly one missed direction at the sharp $\sqrt{d/n}$ scale. Every remaining term contains at least two missed factors and is therefore controlled by the residual second-moment energy. The resulting subspace has dimension depending only on $k$. Exhaustive moment fitting in this constant-dimensional space produces a proper mixture and, together with the dimension-free moment characterization of Gaussian mixtures, achieves the optimal Hellinger rate in polynomial arithmetic time for every fixed $k$.
toXiv_bot_toot
@arXiv_mathST_bot@mastoxiv.pageEmpirical likelihood confidence regions for ordered bivariate means
Naresh Garg
https://arxiv.org/abs/2608.12174 https://arxiv.org/pdf/2608.12174 https://arxiv.org/html/2608.12174
arXiv:2608.12174v1 Announce Type: new
Abstract: Let $\boldsymbol{X}_i=(X_{1i},X_{2i})^\top$ be independent and identically distributed observations with mean $\boldsymbol{\mu}=(\mu_1,\mu_2)^\top$ constrained by $\mu_1\leq\mu_2$. We study empirical-likelihood inference for a fixed mean vector and distinguish it from the previously known test of equality against an ordered alternative. At a fixed interior point, the constrained empirical likelihood ratio has the usual $\chi^2_2$ limit. At a fixed boundary point $(m,m)^\top$, its limit is the chi-bar-square distribution $\tfrac12\chi^2_1 \tfrac12\chi^2_2$. By contrast, profiling the unknown common mean in the equality-versus-order test yields $\tfrac12\chi^2_0 \tfrac12\chi^2_1$, the $k=2$ ordered-mean case of El Barmi (1996). We give an exact reduction of the latter statistic to the empirical likelihood of the paired differences, establish the localization step needed for the fixed-boundary expansion, and derive a local-to-boundary limit showing that interior calibration is not uniform over $n^{-1/2}$-neighborhoods of the boundary. Monte Carlo experiments under Gaussian, Student $t_5$, and shifted log-normal sampling examine fixed, boundary, and local regimes with explicit numerical-failure accounting. Illustrative paired-data analyses show the practical distinction between fixed-candidate confidence regions, directional equality tests, and ordinary scalar empirical-likelihood intervals truncated to the nonnegative parameter space.
toXiv_bot_toot
 @arXiv_qfinTR_bot@mastoxiv.page
Detecting unusual trading patterns on cryptocurrency exchanges by means of complexity measures
Jakub Zwydak, Marcin W\k{a}torek, Jaros{\l}aw Kwapie\'n, Stanis{\l}aw Dro\.zd\.z
https://arxiv.org/abs/2607.13916 https://arxiv.org/pdf/2607.13916 https://arxiv.org/html/2607.13916
arXiv:2607.13916v1 Announce Type: new
Abstract: Artificial transaction generation remains an important source of potential market manipulation on cryptocurrency exchanges, as it may distort reported liquidity and reduce market transparency. This study proposes a diagnostic framework for detecting unusual trading patterns based on complexity and statistical-structure measures derived from high-frequency trade-level data. The analysis considers log-returns, trading volume, and transaction counts, using tail distributions, autocorrelation functions, multifractal characteristics, approximate entropy, and detrended cross-correlations. The methodology is applied to BTC, ETH, and XRP traded on Binance, Bitget, KuCoin, and Kraken over the period from April 1 to June 30, 2025. The results reveal a pronounced anomaly on Bitget for BTC and ETH after mid-May 2025. The number of transactions increases sharply, but there is no proportional increase in traded volume or return fluctuations. This regime is characterised by numerous low-volume trades, weaker autocorrelations, reduced multifractal organisation, higher short-pattern irregularity, and weaker cross-correlations involving the transaction-count series. These features are consistent with a noise-like component in trading activity and may indicate artificially increased transaction counts, although they do not provide direct proof of wash trading. The findings show that complexity-based indicators can be useful for detecting exchange-specific trading anomalies that remain hidden in price-based measures.
toXiv_bot_toot